What recession-proof means for Cyprus property
The phrase “recession-proof” can make property sound safer than it is. If you are weighing a purchase, think instead about how well a particular home, rental market, or project could withstand weaker demand. Cyprus real estate market trends can offer useful context, but they cannot remove the need to assess a specific property.
Resilience is not the same as immunity from falling prices
A resilient market may keep attracting buyers or tenants during a slowdown, but that does not prevent prices from falling. You could still face a longer sale, reduced rent, or fewer offers. Resilience is a matter of degree, and it often depends on the property’s location, affordability, and intended use.
How recessions affect sales, rents, construction, and financing
A downturn can affect several parts of the market at once. Buyers may delay decisions, tenants may seek cheaper homes, lenders may become more cautious, and developers may slow or phase construction. These effects can arrive at different times, so a stable sale price does not necessarily mean rents or project activity are equally strong.
Which market indicators reveal stress earliest
Transaction volumes can weaken before asking prices change, while fewer viewings or longer marketing periods may hint at softer demand. Compare these signals with published price data, such as the quarterly property price indices, rather than relying on listing prices alone. Read several signals together; one quiet month is not enough to establish a trend.
Indicator | What to check | Why it matters |
|---|---|---|
Transactions | Completed sales over time | Shows whether buyers are acting |
Asking prices | Changes in comparable listings | Signals seller expectations |
Rental activity | Rents, vacancies, and time to let | Tests income demand |
Credit conditions | Rates and lending terms | Affects buyer purchasing power |
A gap between asking prices and completed sales may suggest that sellers have not yet adjusted to changed conditions. Use the indicators as clues, not as a forecast on their own.
Why national averages can hide local differences
A national figure blends neighborhoods, property types, and buyer groups. A coastal apartment market may respond differently from a home purchased mainly by local households. For a broader view of the island’s current conditions, you can compare district-level market figures with the area and property type you are considering.
What shapes the Cyprus real estate market trends
The market responds to local economic conditions as well as outside demand. Tourism, household budgets, borrowing costs, and the pace of new construction all affect how easily homes sell or rent. Their influence differs by district and property segment, so it is worth asking which forces matter most for your own purchase.
Tourism and international buyer demand
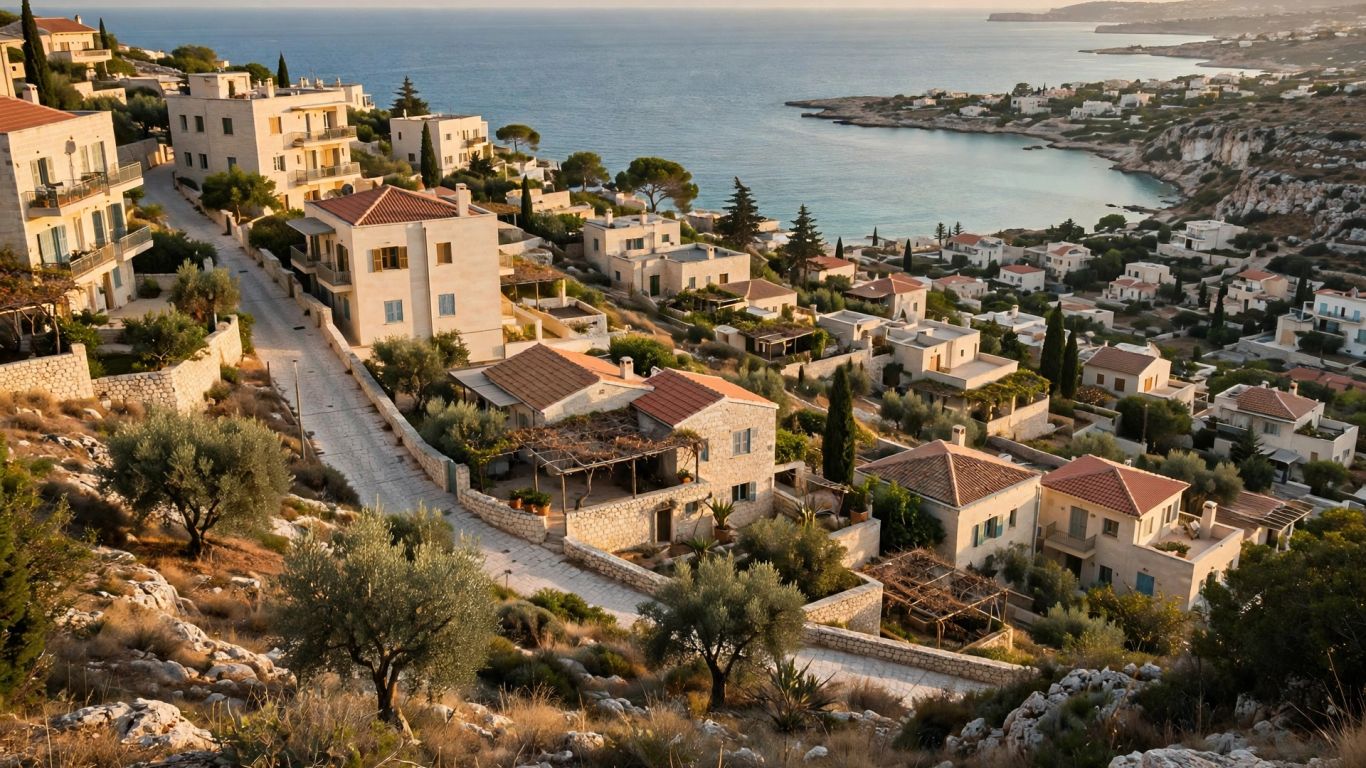
Tourism can support demand for holiday accommodation and homes in visitor destinations, while overseas buyers may bring a different pattern of interest from local households. Neither source is guaranteed to continue at the same pace. If you are assessing an area with a strong visitor economy, consider how it might perform outside the busiest travel periods.
Local incomes, employment, and household borrowing
Local employment and incomes shape what residents can afford to buy or rent. Where household budgets are under pressure, buyers may delay a move or choose a less expensive property. That can leave higher-priced homes exposed to a different set of buyers than properties aimed at local demand.
Interest rates, mortgage access, and credit conditions
When financing costs rise or lenders tighten their terms, some buyers may qualify for smaller loans or decide to wait. That can reduce demand even if people remain interested in a home. Before committing, check the actual terms available to you rather than assuming that financing will remain unchanged.
Construction costs, housing supply, and development pipelines
Material and labor costs influence the amount and timing of new supply. A large pipeline may give buyers more choice, but delays or rising costs can also alter completion schedules and project budgets. Ask what stage a development has reached and what assumptions sit behind its expected delivery.
How different property segments may respond to a downturn
A slowdown rarely affects every kind of property in the same way. A home bought for everyday living has different demand drivers from a holiday rental or an office. That distinction can help you avoid treating the entire island as a single investment proposition.
Residential homes for local buyers
Homes priced within reach of local households may draw on a broader pool of residents than properties dependent on discretionary purchases. Still, affordability and access to mortgages matter. Check whether likely buyers or tenants in the area have the income and financing to support the price you are considering.
Holiday homes and short-term rentals
Holiday homes can be more exposed to travel patterns and seasonal occupancy. If visitor demand softens, income may become less predictable, even when the property remains attractive for personal use. Build your decision around conservative occupancy assumptions, not just the best months of the year.
Commercial property and office space
Commercial demand depends on business activity, location, and the needs of prospective tenants. A changing economy may cause companies to reconsider space or spending, while some locations remain useful to particular industries. Examine the tenant market and likely vacancy period before counting on rent.
New-build developments and off-plan purchases
Buying before completion can involve more uncertainty than purchasing a finished home. You should understand the project’s stage, payment schedule, expected completion, and the consequences of delay. A lower initial price is not enough by itself; the contract and delivery details matter too.
Why resilience varies across Cyprus
Cyprus is not one uniform property market. Each district has its own mix of employers, residents, visitor demand, and available homes. Looking at these local conditions helps you judge whether an area’s demand is diverse or relies heavily on a single source.
Comparing Nicosia, Limassol, Larnaca, and Paphos
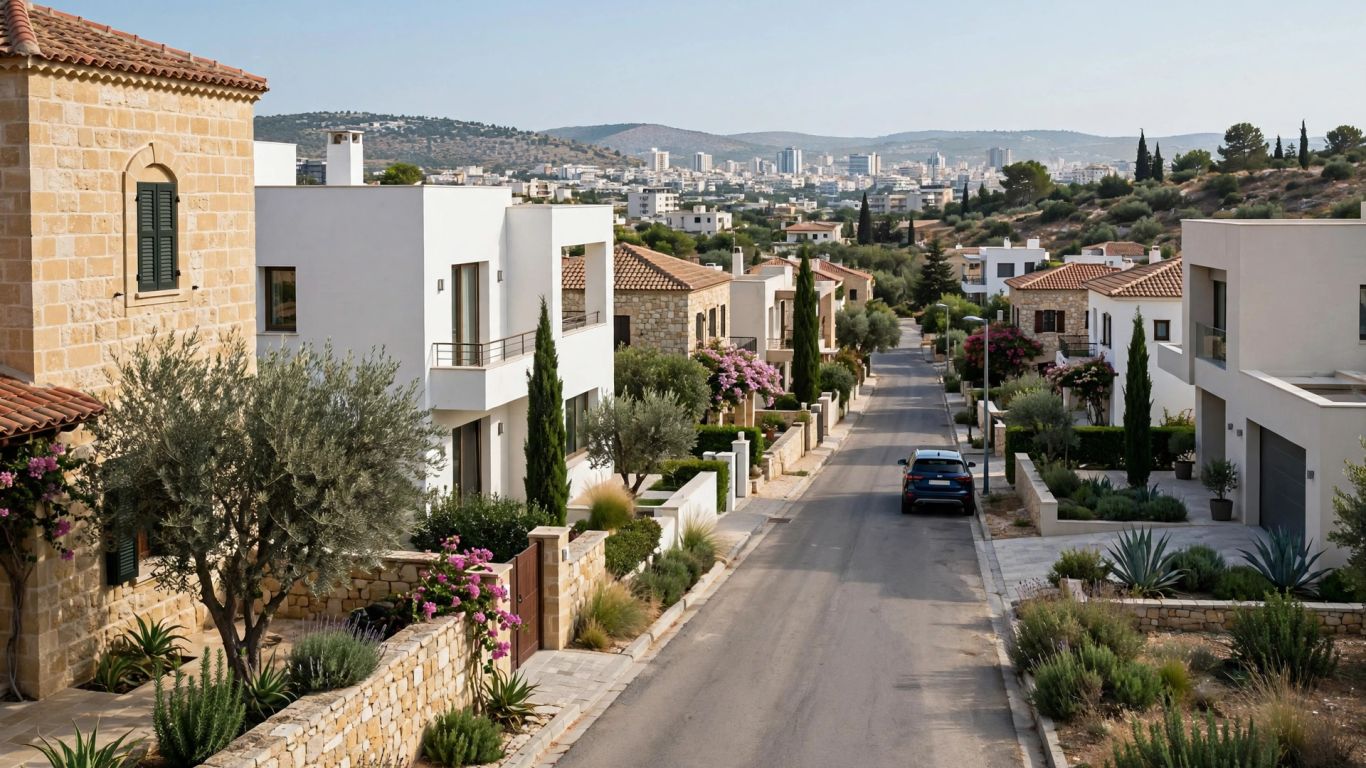
Nicosia, Limassol, Larnaca, and Paphos differ in their urban character, employment base, and exposure to tourism. A useful comparison starts with the exact neighborhood and property type, rather than a broad ranking of districts. Check local transactions and rents against comparable homes before drawing conclusions.
The role of employment and business activity in each district
Where a district has varied employment and business activity, housing demand may draw on more than one group. A narrower local economy can be more vulnerable if a major source of work weakens. Consider who lives and works nearby, and whether the property suits those households.
How tourism exposure affects coastal markets
Coastal locations may attract visitors and overseas buyers, but that can also make some properties more sensitive to travel and seasonal demand. Ask whether the home has a plausible long-term rental audience as well as holiday appeal. The answer may change how much income risk you are willing to take.
Why location, property type, and price point matter
Two homes in the same district can perform differently if one is well connected and realistically priced while the other depends on a narrow buyer pool. Look at condition, running costs, access to services, and nearby competing supply. A property’s individual fit often matters more than a headline market average.
Risks that could weaken the market
No location is insulated from economic and political change. A downturn may combine weaker demand with more expensive finance or slower project delivery, putting pressure on both buyers and owners. Consider how several risks could affect your plans at once, rather than treating each as a remote possibility.
A downturn in tourism or overseas investment
If travel weakens or overseas buyers become less active, some coastal and higher-priced segments may lose a source of demand. That does not mean every property will be affected equally. Check whether local residents and long-term tenants could still support the property’s value and use.
Higher borrowing costs and tighter lending
More expensive loans can reduce what buyers can afford and make refinancing harder. If you rely on borrowing, assess what happens if your rate, deposit, or loan terms differ from your expectations. Leave room in your budget for less favorable financing conditions.
Oversupply, delayed projects, and construction pressures
A concentration of similar homes can make it harder to secure tenants or sell at your preferred price. Construction delays and rising costs may add uncertainty to new projects. Compare planned supply with the number and type of homes that buyers or renters are likely to seek.
Regulatory changes and geopolitical uncertainty
Changes to planning, property ownership, or rental rules can affect costs and demand. Wider geopolitical events may also influence confidence and cross-border investment. Verify current requirements with qualified local professionals and avoid assuming that today’s rules will remain unchanged.
How to assess the market before investing
A careful assessment combines local evidence with your own finances. Start with comparable properties, then consider how your plans would hold up if selling or renting takes longer than expected. The island’s development and affordability pressures also make it useful to look beyond price growth and consider whether local demand can sustain a property over time.
Track transaction volumes alongside asking prices
Compare completed sales with advertised prices for similar properties in the same area. If listings remain high but transactions slow, sellers may need more time to find buyers or reset expectations. Review the direction of both measures over several periods rather than reacting to one snapshot.
Compare rental yields with vacancy and operating costs
A headline rental return does not account for empty periods, repairs, management, insurance, or other expenses. Estimate what remains after costs and test the result against realistic rents. If your return depends on uninterrupted occupancy, the investment may be more fragile than it first appears.
Check financing terms and plan for slower sales
Confirm your borrowing terms, deposit requirements, and monthly obligations before you make an offer. Also consider how long you could hold the property if you cannot sell quickly. A slower exit can be manageable when you have planned for it; it is much harder when funds are needed on a fixed date.
Stress-test cash flow against lower rents and longer vacancies
Run a simple downside scenario before committing. For example, test whether your budget still works if rent falls, a tenant leaves, or a repair arrives at the same time. A few straightforward checks can reveal how much financial breathing room you actually have:
Reduce expected rent and recalculate monthly income.
Allow for a longer vacancy between tenants.
Add maintenance and management costs to the estimate.
Check whether you can cover loan payments without rent.
If the plan remains manageable under these conditions, you have a clearer view of its risks. If it does not, reconsider the price, financing, or property type before proceeding.
Verify property title, planning status, and ownership costs
Before purchase, have the title, planning status, and relevant ownership costs checked by qualified professionals. Confirm what is included in the sale and whether any approvals or obligations affect your intended use. Careful due diligence cannot eliminate market risk, but it can help you avoid preventable surprises.
Anna Georgiou
Head of Client Relations
BERKOS is an integrated real estate group in Limassol, Cyprus, covering development, construction, property management and the legal and financial work around them.